A single line in a Treasury briefing document can turn a profitable Lake District cottage into a loss-making liability overnight. That is the scenario now facing thousands of holiday let owners across the North West, after reports emerged that ministers are weighing up a tax change that could add nearly £5,000 a year to the cost of running a typical holiday let.
With the Autumn Budget set for Wednesday 28 October 2026, holiday let council tax reclassification Budget 28 October 2026 Manchester second home owners concerns have moved from speculation to a live planning issue for anyone with property in the Lakes, the Peak District, the Lancashire coast, or a city-centre short-let flat. Chancellor John Healey, under Prime Minister Andy Burnham, will deliver the statement, and property taxation is firmly on the list of possible measures.
This article sets out what has actually been reported, what remains rumour, and what Manchester-based owners should do before the Budget lands, regardless of the outcome.
Key Takeaways
- Landlord Today reported on 5 October 2026 that the government is considering moving holiday lets from business rates onto council tax, exposing them to second-home premiums of up to 100%.
- Industry analysis from Finest Retreats, a lobbying estimate, not government data, suggests the change could cut a typical holiday let's annual profit from £4,976 to just £192 before mortgage costs.
- Council tax bands are based on a fixed valuation band; business rates use a rateable value linked to trading potential, the two systems value property very differently.
- No stamp duty changes are expected at this Budget, but a mansion tax threshold and capital gains tax changes remain rumoured and unconfirmed.
- An independent RICS valuation and condition survey now, before any change of use, gives owners a defensible evidence base whatever the Budget decides.
Holiday Let Council Tax Reclassification Budget 28 October 2026 Manchester Second Home Owners: What's Being Proposed
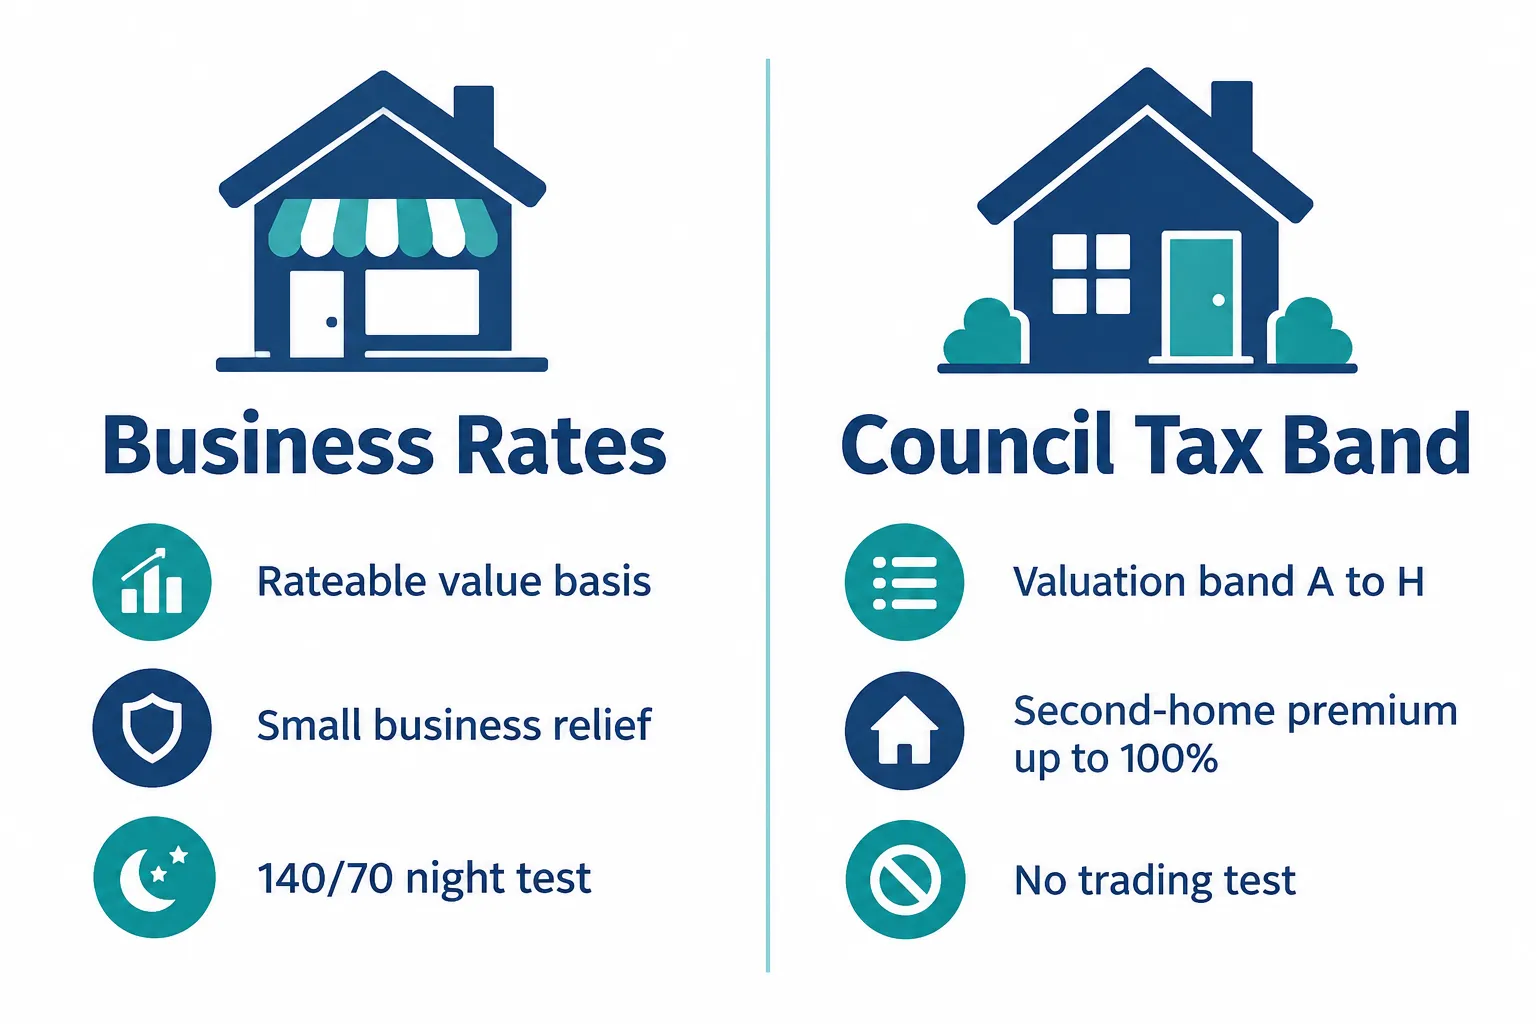
According to Landlord Today's report on 5 October 2026, the government is actively considering reclassifying holiday lets from business rates to council tax. Currently, a holiday let qualifies for business rates, and often small business rate relief, provided it is available to let for 140 nights a year and actually let for at least 70 of those nights. Move that same property onto council tax, and it could be caught by the second-homes premium that roughly 84% of English councils now apply, at rates of up to 100% on top of the standard charge.
This would not be the first tightening of the rules for owners of holiday lets and second homes. The furnished holiday lettings (FHL) tax regime, which gave these properties favourable income tax and capital allowances treatment, was abolished from April 2025. Second-home council tax premiums of up to 100% have also been permitted in England since April 2025. Wales and Scotland have already introduced visitor levies on overnight stays. Taken together, the direction of travel has been consistently towards higher costs for holiday let owners, and this latest proposal would be the most significant step yet.
It is important to stress: this is a proposal under consideration, not a confirmed policy. The government has ruled out changes to stamp duty at this Budget, but other property tax measures, including a possible mansion tax threshold and changes to capital gains tax, are rumoured without official confirmation. Owners should treat all of this as planning information, not settled fact, until the Chancellor sits down on 28 October.
The Finest Retreats Industry Analysis: Read With Caution
Finest Retreats, described as the UK's largest family-owned holiday lettings management company, has published analysis intended to lobby against the change. Its figures should be read as an industry argument, not independent government data, but they illustrate the scale of what is being discussed.
| Measure | Finest Retreats estimate |
|---|---|
| Local spend: housekeeper wages and trades | £10,178 per year |
| Local spend: guest spending in the area | £7,448 per year |
| Total local economic contribution | £17,626 per year |
| Additional council tax under reclassification | £4,784 per year |
| Annual profit before change (before mortgage costs) | £4,976 |
| Annual profit after change (before mortgage costs) | £192 |
The headline claim, that a typical holiday let's profit could fall by roughly 96%, is a striking number designed to influence the Budget debate. Whether or not the final policy matches this scenario, it gives Manchester owners a useful stress test for their own figures ahead of 28 October.
Council Tax Bands vs Business Rates: Why the Difference Matters
The two systems do not just charge different amounts, they value property on entirely different bases, and that distinction matters enormously for anyone deciding whether to sell, convert, or keep trading.
Business rates are based on rateable value, an estimate of the property's annual trading potential as a holiday letting business. It reflects income-generating capacity, location, and letting performance.
Council tax is based on a fixed valuation band (A to H in England), set by reference to the property's capital value at a point in time, regardless of how it is used or how much income it generates. A three-bedroom cottage in a Band F area pays the same council tax whether it is let 300 nights a year or stands empty.
This means reclassification would, in effect, decouple the tax charge from trading performance entirely. A struggling holiday let in a high council tax band could end up paying more tax under the new system than a thriving one in a lower band, the opposite of how business rates currently work. For owners considering whether to keep trading, this uncertainty is itself a strong argument for getting a current, independent view of a property's position, see recent analysis of rental yields across Manchester and the North West for context on how returns are shifting across the wider market.
Change of Use: From Holiday Let to Long-Term Residential Letting
For many owners, the sensible contingency plan is converting a holiday let into a standard long-term residential tenancy. This is not simply a paperwork exercise, it carries real valuation, mortgage, and legal consequences.
Valuation impact. A holiday let is often valued (for lending and insurance purposes) partly on its trading income and seasonal demand. A long-term let is valued more conventionally, based on comparable residential sales and rents in the area. These figures can diverge significantly, particularly for coastal or Lakes properties with strong seasonal premiums. Recent Manchester and North West house price data shows how local market conditions vary street by street, which is exactly why a generic online estimate is not sufficient for this kind of decision.
Mortgage terms. Holiday let mortgages typically carry different terms, rates, and lender covenants than standard buy-to-let products. Switching use without informing the lender can breach mortgage conditions. Owners should check whether their existing finance permits a change of use before committing.
Renters' Rights Act obligations. Moving to a standard residential tenancy brings the property within the scope of the Renters' Rights Act framework, including tenancy structure, deposit protection, and landlord responsibilities that differ from short-let holiday arrangements. Owners unfamiliar with these obligations should take advice before advertising a former holiday let as a long-term rental, particularly given the wider pressure on Manchester landlords from rising rents and falling supply this autumn.
Why an Independent RICS Valuation Matters Before 28 October
Whatever the Budget announces, owners weighing up whether to sell, convert, or continue trading need a reliable, defensible figure for the property's current value and condition. A formal Red Book valuation from a RICS-regulated surveyor provides:
- An independent assessment unaffected by lender or agent incentives
- A clear record of value as at a specific date, useful evidence if tax treatment changes retrospectively affect decisions
- A basis for negotiating with lenders if a change of use is being considered
- Supporting evidence for capital gains tax calculations if a sale follows
"Owners making decisions based on Budget speculation need facts, not forecasts. A current valuation and condition record is the one thing that doesn't change, whatever the Chancellor announces."
For a wider view of how North West property values are moving this autumn, see the latest regional house price divergence data showing Manchester's performance against the national picture.
Documenting Property Condition Before Any Change
Beyond valuation, a formal condition record matters just as much, particularly for properties that may switch from holiday letting to long-term residential use, or go to market.
- A building survey or snagging-style condition report establishes a baseline before tenants, buyers, or new mortgage lenders get involved
- It protects owners against later disputes over wear and tear between holiday-let use and residential tenancy
- It supports insurance renewal discussions where use of the property is changing
- It provides useful evidence if the property needs updating to meet rental standards under current letting law
Commissioning this work now, ahead of 28 October, means owners are not scrambling for documentation after the Budget outcome is known, whichever direction it takes.
Frequently Asked Questions
Has the government confirmed holiday lets will move to council tax?
No. Landlord Today reported on 5 October 2026 that this is under consideration ahead of the Budget. It has not been confirmed as policy.
What is the second-homes council tax premium?
Since April 2025, English councils have been permitted to charge up to 100% extra council tax on second homes. Landlord Today's reporting notes that roughly 84% of English councils now apply some form of this premium.
Are the Finest Retreats figures official government estimates?
No. They are industry analysis produced by Finest Retreats, a holiday lettings management company, as part of lobbying against the proposed change. They should be treated as one side's estimate, not independent data.
Will stamp duty change at this Budget?
The government has ruled out stamp duty changes at the 28 October 2026 Budget. Other property tax measures, including a possible mansion tax threshold and capital gains tax changes, are rumoured but unconfirmed.
What happens to the 140/70 night letting rule if reclassification goes ahead?
This has not been detailed in current reporting. If holiday lets move fully to council tax, the business rates occupancy test may become less relevant, but no specifics have been confirmed.
Should I get a valuation before the Budget or wait for the announcement?
Getting an independent valuation and condition survey now means owners have a dated, defensible record of their property's position regardless of what is announced on 28 October.
Conclusion
The proposal to shift holiday lets from business rates onto council tax is, for now, exactly that, a proposal. But the direction of recent policy, from the end of FHL tax status to second-home premiums and visitor levies, suggests owners should not assume the status quo will hold indefinitely. For Manchester and North West owners with property in the Lakes, the Peak District, the Lancashire coast, or city-centre short lets, the sensible approach is to model the Finest Retreats scenario against actual trading figures, check mortgage terms before considering any change of use, and understand Renters' Rights Act obligations if converting to a long-term let.
Most importantly, secure an independent, dated valuation and condition record before 28 October. Manchester Surveyors provides RICS Red Book valuations, building surveys, and condition reports for holiday let and second-home owners across Greater Manchester and the North West, giving a clear evidence base for whatever decision the Budget prompts. Contact Manchester Surveyors today to arrange a valuation or condition survey ahead of the Autumn Budget.
holiday let council tax, council tax reclassification, Autumn Budget 2026, second home owners, Manchester property, holiday lets North West, RICS valuation, furnished holiday lettings, Renters Rights Act, business rates, Lake District holiday cottages, change of use property