Last updated: September 17, 2026
Quick Answer
Manchester's property market is holding steady after the Bank of England kept Bank Rate on hold today. Median sale prices sit around £235,000, asking prices have eased slightly rather than fallen sharply, and homes are still going under offer in roughly 12 weeks. Rental yields of 5% to 7% and regeneration in NOMA, Ancoats and MediaCityUK continue to pull in northern buyers, first-time purchasers and buy-to-let landlords despite mortgage rates that remain well above pre-2022 levels.
Key Takeaways
- The median Manchester sale price over the 12 months to 1 September 2026 was £235,000, far below southern averages.[2]
- Median asking prices in mid-September 2026 sit at £250,000, with most homes priced between £190,000 and £375,000.[1]
- Properties typically go under offer in around 12 weeks, a sign of steady rather than frantic demand.[3]
- Average monthly rent in Manchester reached £1,373 in August 2026, supporting gross yields many landlords quote at 5% to 7%.[10]
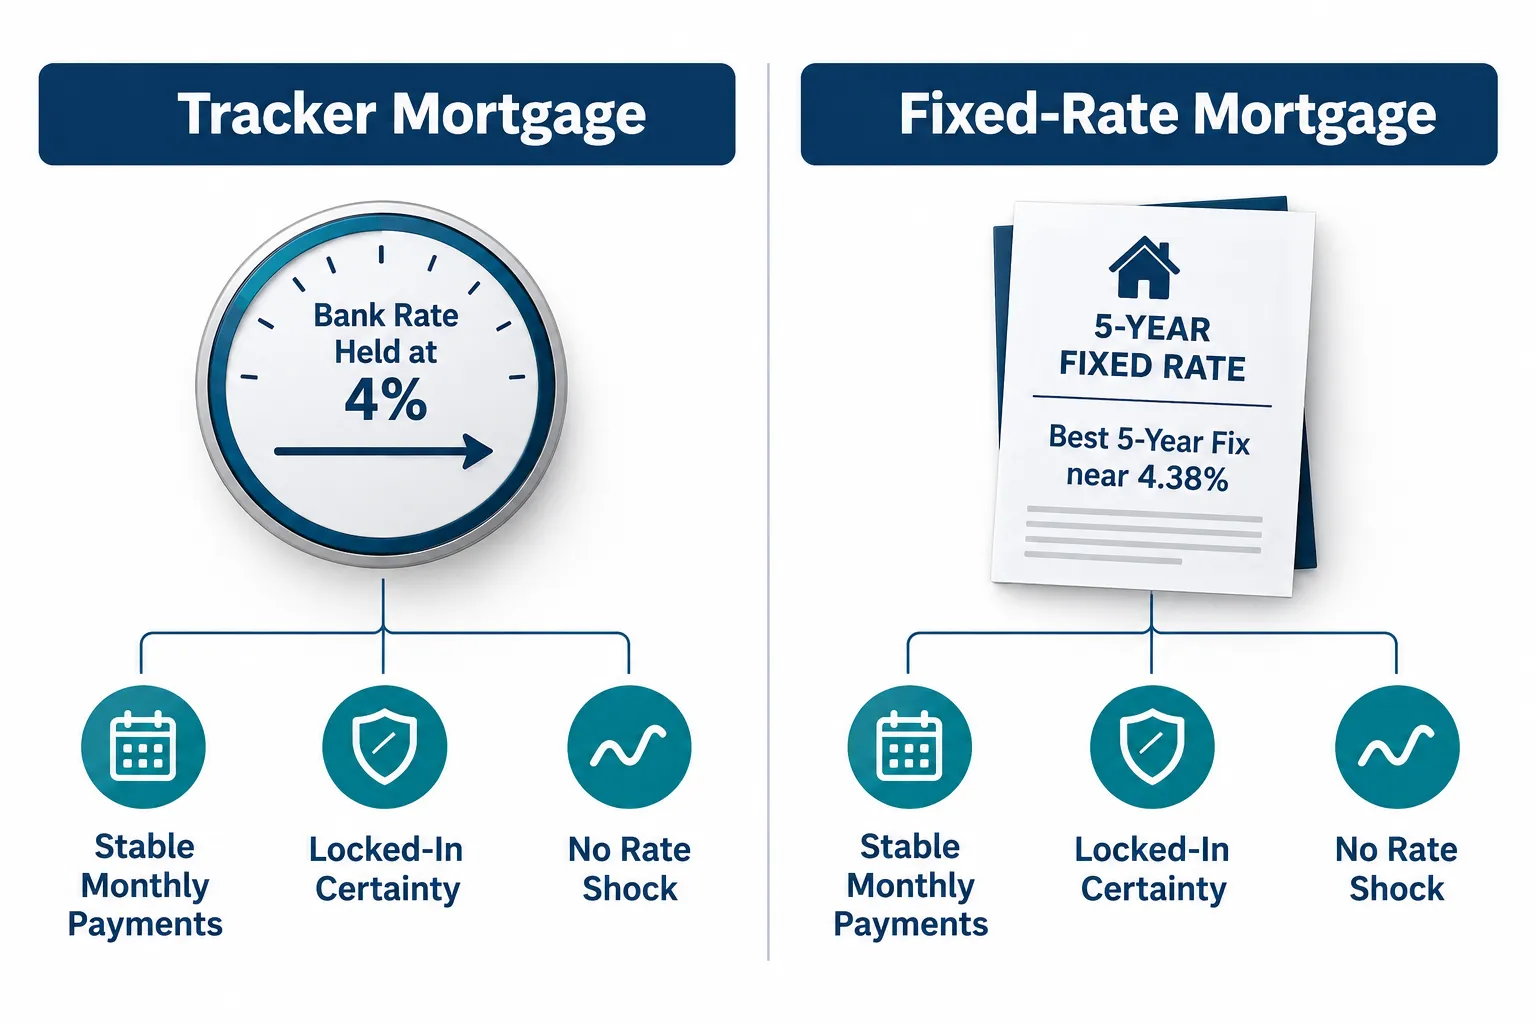
- The best five-year fixed mortgage deals are near 4.38%, though the average five-year fix was still around 5.18% in mid-August.[4][8]
- Nationwide's national data shows house prices up just 1.6% year-on-year in August 2026, calling the market "steady, not surging".[5]
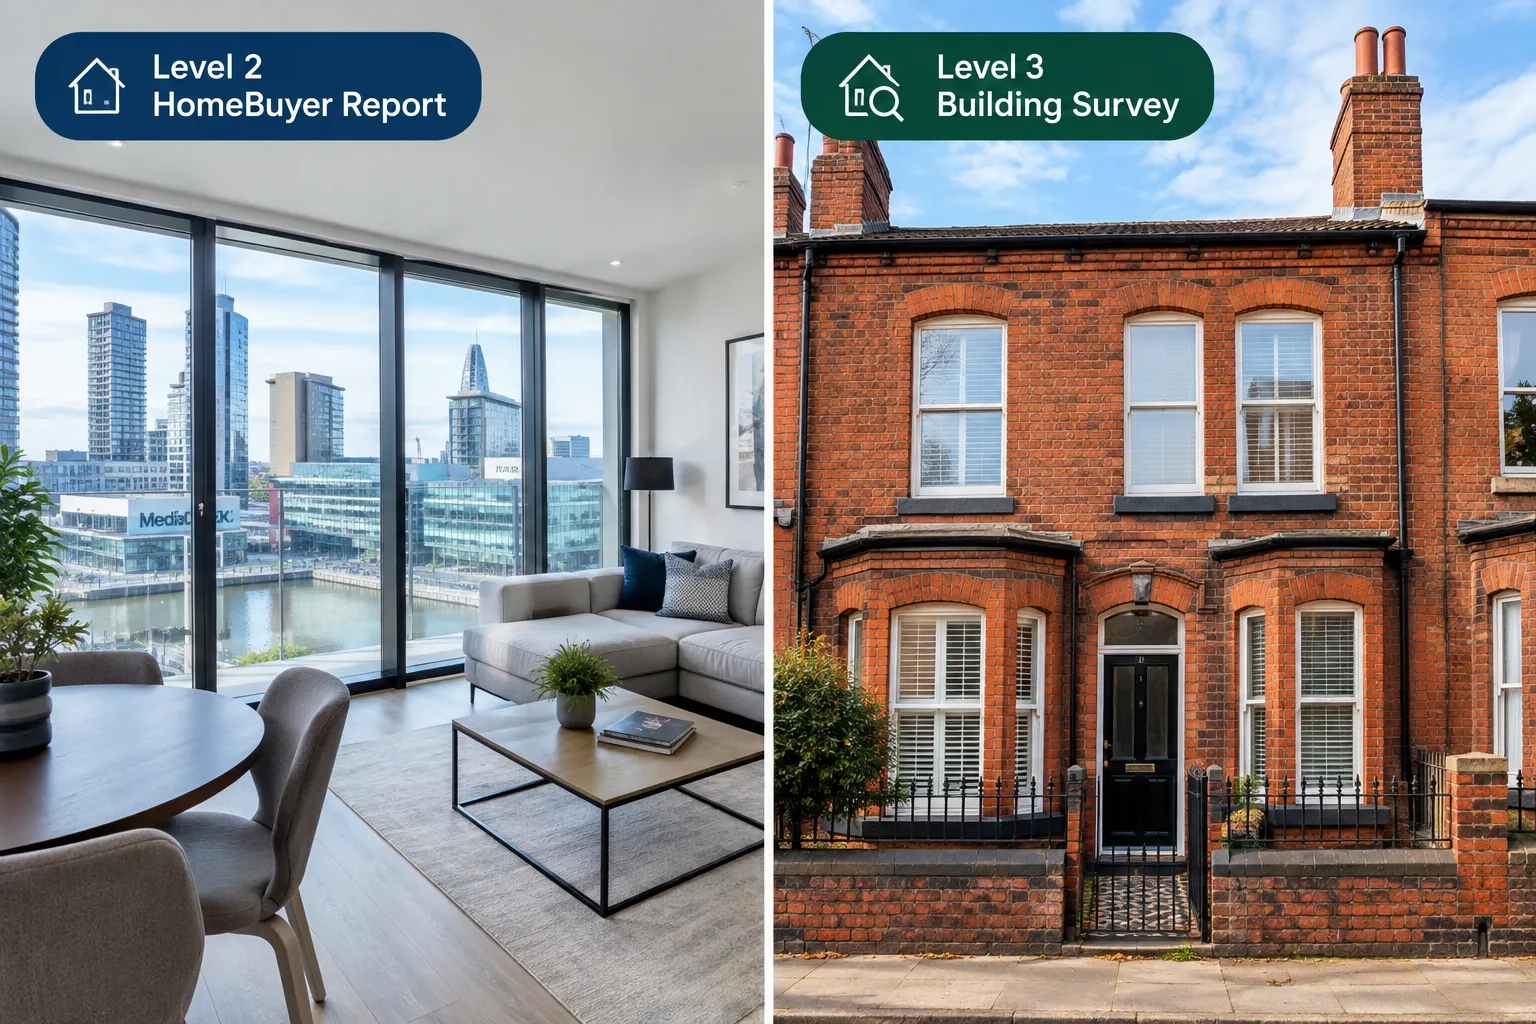
- New-build apartments in NOMA and MediaCityUK are driving Level 2 HomeBuyer Report demand; Victorian terraces in areas like Ancoats and Chorlton are driving Level 3 Building Survey demand.
Manchester Property Market September 2026: What Happened to House Prices Last Month
Manchester house prices moved only modestly in September 2026, with asking prices easing rather than crashing, while listing prices for homes coming to market actually nudged up. This points to a market adjusting to higher borrowing costs, not one in retreat.
Across Greater Manchester, transaction data for the 12 months to 1 September 2026 show a median sale price of £235,000 across 7,040 recorded deals.[2] Separately, market-tracking data for September 2026 put the average asking price at roughly £286,064 and the average listing price at £292,411, reflecting a mix of older and newly listed stock.[3] Over the past six months, asking prices in Manchester have eased by about 1.8%, even as the average listing price crept up 1.88%, which suggests sellers are trimming expectations on existing listings while newer, sometimes higher-specification stock keeps coming to market.[3]
Compared with August, the picture is one of gentle cooling, not collapse. Nationally, Rightmove data cited in early-September analysis show UK asking prices falling 2% in the month to August 2026, from £372,359 to £364,999, the biggest August drop on record.[5][6] Manchester's smaller, steadier adjustment stands out against that national backdrop.
Why Did the Bank of England Hold Interest Rates in September 2026, and What Does It Mean for the North
The Bank of England held Bank Rate at 4% today because inflation is still judged to be on a path back towards the 2% target, and the Monetary Policy Committee remains split on how quickly to move. That caution is filtering through to mortgage pricing and, in turn, to buyer confidence in northern cities like Manchester.
At its most recent formal vote, six members of the MPC backed holding rates while three preferred an increase, extending a run of consecutive holds through the summer.[5][7][11][12] A Reuters survey referenced in a September 2026 housing-market note found that almost 90% of economists expected another hold at today's meeting, with no change anticipated for the rest of the year.[5] RICS's August 2026 market update echoes this, noting that policy is expected to stay broadly stable even though the committee remains divided.[9]
For northern buyers, a held rate does not mean cheaper mortgages overnight. Moneyfacts data for 15 August 2026 show the average two-year fixed mortgage rate at 5.32% and the average five-year fix at 5.18%, both slightly higher than the previous week.[4][8] Best-buy five-year deals, however, are available nearer 4.38% for well-qualified borrowers with larger deposits. Tracker mortgage holders saw no change to monthly payments at all, since their rate is tied directly to Bank Rate.[4]
Decision rule: if a mortgage deal is due to expire within the next six months, it is generally worth locking in a five-year fix now rather than waiting, because further cuts are not guaranteed and rate stability itself has value for household budgeting.
How Does the BoE Rate Hold Affect the Northern Property Market
A held Bank Rate mainly affects the northern property market through borrower psychology and affordability calculations rather than through an immediate price shock. Buyers now know what their monthly costs will look like for the next year, which supports continued transaction volumes even without a rate cut.
- Affordability stays tight but predictable. Fixed-rate costs remain elevated compared with 2021, but stability means buyers can plan rather than delay indefinitely.
- Northern price gaps widen the appeal. With Manchester's median sale price at £235,000 against far higher southern benchmarks, monthly repayments go further even at today's rates.[2]
- Rental demand cushions landlords. Average rent of £1,373 a month in August 2026 keeps yields attractive even where mortgage costs have risen.[10]
A common mistake is assuming a rate hold signals imminent cuts. In fact, the RICS and Reuters-based commentary both point to a prolonged period of stability rather than a quick move lower, which is why demand is holding steady rather than surging back to 2021 levels.[5][9]
Manchester House Prices September 2026 Compared to August, and Is Now a Good Time to Buy
Manchester prices in September 2026 are broadly flat against August, with small asking-price adjustments rather than sharp swings, and for many buyers this counts as a reasonable entry point rather than a reason to wait. Whether now is a good time to buy depends on individual circumstances, but the underlying signals are supportive.
Sale times of around 12 weeks to go under offer show a market with real buyer interest, not desperation on either side.[3] Average estate agent fees sit near 1.3%, in line with recent norms.[3] Choose to buy now if a mortgage offer can be secured at a rate close to the current best-buy five-year fix, if the property fits a five-year-plus holding horizon, and if the deposit is ready. Choose to wait if a rate reduction is essential to affordability, since further short-term cuts are not the base case according to current economist surveys.[5]
What's the Average Cost of a House in Manchester Right Now
The average cost of a house in Manchester right now sits in the £235,000 to £292,000 range depending on the measure used, with a median asking price of £250,000 across homes currently for sale.[1][2][3]
| Metric | Manchester (2026) | Source |
|---|---|---|
| Median sale price (12 months to 1 Sept) | £235,000 | [2] |
| Median asking price (15 Sept) | £250,000 | [1] |
| Average asking price | £286,064 | [3] |
| Average listing price | £292,411 | [3] |
| Typical asking price range | £190,000,£375,000 | [1] |
| Average monthly rent | £1,373 | [10] |
By property size, average sold prices in September 2026 were roughly £169,378 for one-bed homes, £239,296 for two-beds, £324,465 for three-beds, £474,872 for four-beds, and £717,925 for five-bed properties, showing how much choice exists across budget levels.[3]
Why Are Northern Buyers Still Interested in Manchester Property
Northern buyers remain drawn to Manchester because regeneration in NOMA, Ancoats and MediaCityUK keeps adding good-quality stock and jobs, while prices stay well below southern equivalents. That combination of value and visible investment is hard to match elsewhere in the region.
- NOMA continues to deliver office-led regeneration around the city centre, supporting demand for nearby flats.
- Ancoats has become a magnet for buyers wanting converted mill apartments alongside restored Victorian terraces.
- MediaCityUK in Salford keeps drawing media and tech employment, feeding steady rental demand for new-build apartments.
Buyers priced out of London and the South East find that a similar salary stretches much further here, and the median £235,000 sale price makes that gap concrete rather than theoretical.[2]
How Does Manchester Compare to the National Property Market in September 2026
Manchester is outperforming the wider UK market on relative resilience, even though national price growth is itself modest. National asking prices fell 2% in the month to August 2026, the sharpest August drop on record, while Manchester's own asking-price adjustment over six months was a gentler 1.8%.[3][5][6]
Nationwide's August 2026 House Price Index shows UK prices up just 1.6% year-on-year and 0.2% month-on-month, a pattern described as "steady, not surging".[5] Against that backdrop, Manchester's combination of a sub-£250,000 median asking price, 12-week sale times and consistent rental demand marks it out as one of the steadier northern markets, rather than one riding a short-term bubble.[1][3][5]
What Types of Properties Are Selling Best in Manchester in 2026
New-build apartments in regeneration zones and well-located Victorian terraces are both selling strongly in Manchester, but they attract different survey needs and different buyer types. Understanding which survey applies helps buyers budget correctly before making an offer.
- New-build and modern apartments (NOMA, Ancoats conversions, MediaCityUK) commonly need a Level 2 HomeBuyer Report, suited to properties in reasonable structural condition where the main concerns are finish quality, service charges and lease terms.
- Victorian and older terraced stock (common across Chorlton, Levenshulme and parts of Salford) more often needs a Level 3 Building Survey, given higher risks around roofs, damp, subsidence and outdated wiring.
Quick example: a buyer purchasing a 10-year-old flat near MediaCityUK for straightforward reassurance would typically choose a Level 2 report, while a buyer on a pre-1919 terrace in Ancoats facing a higher price tag and older materials would be better served by the fuller Level 3 survey.
Will Manchester Property Prices Go Up or Down After the Rate Hold
Manchester prices are more likely to stay broadly flat to modestly positive over the coming months than to fall sharply, based on current national and local trends. A rate hold removes the risk of a sudden mortgage cost spike, which tends to support rather than undermine demand.
Nationwide's national growth figure of 1.6% year-on-year in August 2026 gives a useful ceiling for expectations, while Manchester's own six-month asking-price dip of 1.8% suggests the market has already absorbed most of the recent affordability pressure.[3][5] Are prices expected to drop after the BoE decision? The evidence points to stabilisation rather than a fresh decline, since economists surveyed ahead of today's meeting overwhelmingly expected rates to stay on hold for the rest of the year, removing one of the main triggers for a further price correction.[5]
Who Is Buying Property in Manchester in 2026, and Where Are the Best Areas to Invest
Buyers in Manchester in 2026 span first-time purchasers priced out of the South, relocating professionals drawn by MediaCityUK and NOMA employers, and buy-to-let landlords chasing yield. Each group tends to favour a slightly different part of the city.
- First-time buyers: often look towards Salford, Openshaw and outer suburbs where prices sit below the £235,000 median.[2]
- Professionals and relocators: gravitate to NOMA, Ancoats and city centre apartments near transport links.
- Buy-to-let landlords: focus on areas with strong rental demand, where average rent of £1,373 a month supports yields commonly quoted between 5% and 7%.[10]
For investment, NOMA, Ancoats and MediaCityUK stand out for regeneration-driven capital growth, while established terraced areas such as Chorlton and Levenshulme offer steadier, lower-turnover rental demand.
How Much Deposit Do I Need to Buy in Manchester in September 2026
Most lenders in Manchester in September 2026 ask for a minimum deposit of 5% to 10% of the purchase price, though better rates, including deals close to the 4.38% best-buy five-year fix, are usually reserved for borrowers with 15% to 25% deposits. On a median £235,000 sale price, that means a deposit ranging from roughly £11,750 at 5% to £58,750 at 25%.[2][4]
Buy-to-let purchases typically require larger deposits, often 25% or more, reflecting lender caution around rental income cover at current mortgage rates.[4][8]
Practical Guidance for Buyers, Sellers, Remortgagers and Landlords
Different groups need different priorities in this market, and getting the order of decisions right matters more than trying to time the exact bottom of the cycle.
- Buyers: get a mortgage offer in principle before viewing, and budget for either a Level 2 HomeBuyer Report on newer flats or a Level 3 Building Survey on older terraces.
- Sellers: price close to recent local sold data rather than aspirational asking prices, since Manchester's 12-week average sale time rewards realistic pricing.[3]
- Remortgagers: compare five-year fixed deals now, since best-buy rates near 4.38% may not last if lender competition eases.[4]
- BTL landlords: stress-test cash flow against average rents of £1,373 a month and mortgage rates around 5.18% to 5.32%, not just the best-buy headline rate.[4][10]
Frequently Asked Questions
What is the current average house price in Manchester?
Median sale prices sit around £235,000, with a median asking price of £250,000 for homes currently on the market in mid-September 2026.[1][2]
Did the Bank of England cut or hold interest rates in September 2026?
The Bank of England held Bank Rate at 4% today, extending a run of holds through 2026 as inflation is expected to keep easing towards target.[5][7][9]
Are Manchester house prices falling in 2026?
Asking prices have eased by around 1.8% over six months, but this is a gentle adjustment, not a collapse, especially against the national 2% monthly drop recorded in August 2026.[3][5][6]
What rental yield can landlords expect in Manchester?
Local agents commonly quote gross rental yields between 5% and 7%, supported by average monthly rents of £1,373 recorded in August 2026.[10]
Is a Level 2 or Level 3 survey needed for a Manchester property?
Newer apartments in areas like MediaCityUK usually suit a Level 2 HomeBuyer Report, while older Victorian terraces in areas like Ancoats generally need a fuller Level 3 Building Survey due to higher structural risk.
How much deposit is typically needed in Manchester right now?
Most residential buyers need 5% to 10% minimum, though 15% to 25% deposits unlock the best available rates, including five-year fixes near 4.38%.[4]
Conclusion
Manchester's property market is proving one of the steadier stories in the UK this September, holding firm on demand while national asking prices post their sharpest August fall on record. The Bank of England's decision to keep Bank Rate at 4% today removes a major source of near-term uncertainty, and while average mortgage rates remain above the best-buy 4.38% five-year deals, buyers now have a clearer basis for planning.
Next steps: buyers should get a mortgage offer in principle and budget for the right type of survey before making an offer; sellers should price against recent local sold data rather than last year's asking prices; remortgagers should compare five-year fixes now rather than waiting for a cut that may not come this year; and landlords should stress-test yields against average, not best-buy, mortgage rates. Manchester's mix of affordability, regeneration and rental strength gives all four groups a workable path through the rest of 2026.
References
[1] Manchester – useperch.co.uk
[2] Manchester – moveinsights.co.uk
[3] Manchester – getagent.co.uk
[4] Mortgage Rates In August 2026 Whats Actually Changed – london-fs.com
[5] Uk Housing Market September 2026 – ireis.co.uk
[6] August 2026 Uk Property Market Update Forecasts Cut Rents Wrwye – linkedin.com
[7] Market Update August 2026 – bsa.org.uk
[8] Uk Interest Rate Pause What August 2026 – baba-int.com
[9] Uk Economy Property Market Update August 2026 – rics.org
[10] E08000003 – ons.gov.uk
.cg-wrap{font-family:Arial,Helvetica,sans-serif;max-width:520px;margin:0 auto;padding:16px;background:#f4f6f8;border-radius:10px;border:1px solid #d8dde2}
.cg-wrap h2{font-size:18px;color:#0b2e4f;margin:0 0 10px}
.cg-row{margin-bottom:10px}
.cg-row label{display:block;font-size:13px;color:#33414f;margin-bottom:4px;font-weight:bold}
.cg-row input{width:100%;padding:8px;border:1px solid #b9c2ca;border-radius:6px;font-size:14px;box-sizing:border-box}
.cg-btn{background:#0b2e4f;color:#fff;border:none;padding:10px 14px;border-radius:6px;font-size:14px;cursor:pointer;width:100%}
.cg-btn:hover{background:#154a7a}
.cg-results{margin-top:14px;background:#fff;border:1px solid #d8dde2;border-radius:8px;padding:12px}
.cg-results p{margin:4px 0;font-size:14px;color:#1c2a36}
.cg-results span{font-weight:bold;color:#0b2e4f}
.cg-note{font-size:11px;color:#5a6773;margin-top:10px}
Manchester Buy-to-Let Yield & Affordability Estimator
Enter figures above and press Calculate.
Estimate only, based on interest-only calculation. Not financial advice. Compare actual lender quotes before deciding.
function cgCalc(){
var price=parseFloat(document.getElementById(‘cg-price’).value)||0;
var depPct=parseFloat(document.getElementById(‘cg-deposit’).value)||0;
var rent=parseFloat(document.getElementById(‘cg-rent’).value)||0;
var rate=parseFloat(document.getElementById(‘cg-rate’).value)||0;
var deposit=price*(depPct/100);
var loan=price-deposit;
var monthlyInterest=(loan*(rate/100))/12;
var annualRent=rent*12;
var grossYield=price>0?((annualRent/price)*100):0;
var cashflow=rent-monthlyInterest;
var out=document.getElementById(‘cg-out’);
out.innerHTML=
‘
Deposit needed: £’+deposit.toLocaleString(undefined,{maximumFractionDigits:0})+’
‘+
‘
Loan amount: £’+loan.toLocaleString(undefined,{maximumFractionDigits:0})+’
‘+
‘
Estimated monthly interest cost: £’+monthlyInterest.toLocaleString(undefined,{maximumFractionDigits:0})+’
‘+
‘
Gross rental yield: ‘+grossYield.toFixed(2)+’%
‘+
‘
Rent minus interest (rough monthly cashflow): £’+cashflow.toLocaleString(undefined,{maximumFractionDigits:0})+’
‘;
}